Your Local Mortgage Lender
Located in Sarasota, Florida
Personalized Mortgage Experience
Dennis Wells offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Sarasota, Florida.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
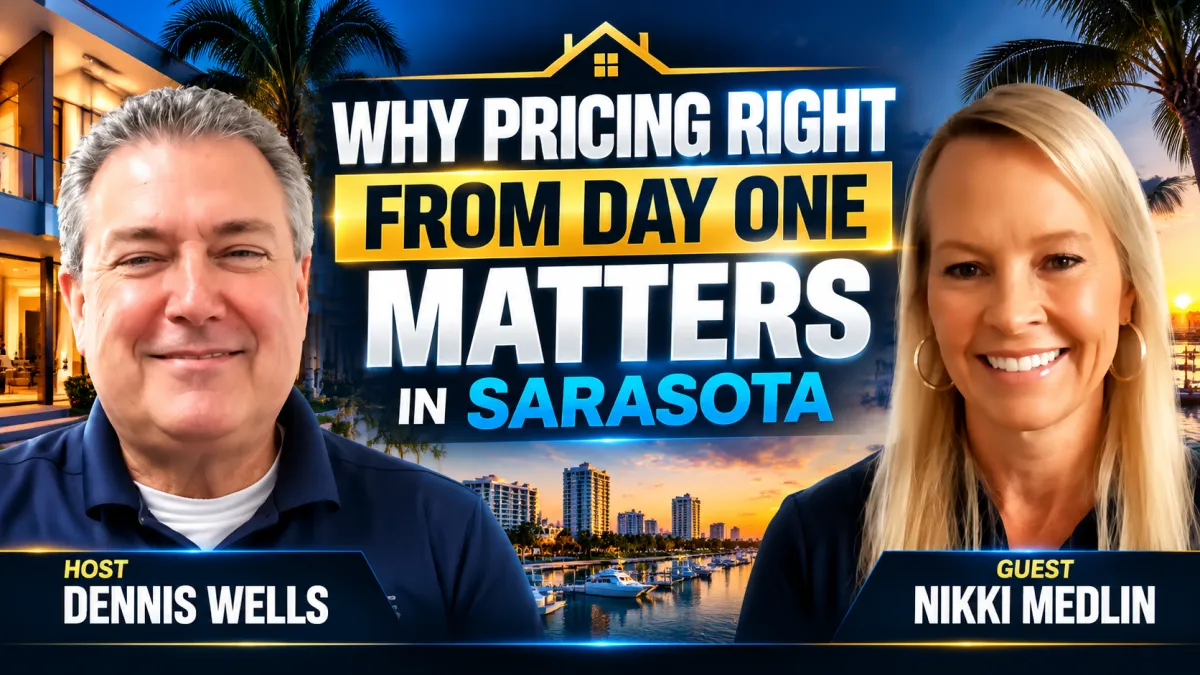
Real Estate Insider: Dennis Wells Talks Sarasota Market Pricing Strategy With Appraiser Turned Realtor Nikki Medlin
The Realtor Who Spent Thirty Years Looking at Properties Before She Ever Listed One
Dennis Wells welcomed Nikki Medlin of Preferred Shore Realty to the Real Estate Insider podcast for a conversation built around one of the most genuinely unusual backgrounds in the Sarasota real estate market. Nikki spent over thirty years as a real estate appraiser before ever selling a house. She started in a bank appraisal department in 1986 right out of high school, worked her way into the appraiser role, spent decades there and with an independent firm, and eventually moved to Florida for the sunshine.
She intended to get her appraiser's license in Florida and work part-time. When she discovered the reciprocity process would take two years she got her real estate sales license in three weeks instead. She had always wanted to sell real estate but was too afraid to make the transition while she was in the appraisal world. The Florida move removed that hesitation.
Her first experience active selling was with a builder who turned out to be going bankrupt and leaving the area. She spent three months staffing his model until she figured out what was happening and transferred her license. She started genuinely selling in 2024 and has been building her practice since with an edge that very few agents in any market can claim.
Why Three Decades of Appraising Changes How You See Real Estate
The distinction Nikki draws between her background and a standard sales background is not about years of experience. It is about the specific skills that appraising develops.
She understands that comparable sales are history. Not the current market. Not a prediction of where things are going. A record of where they were when those transactions closed. Most agents present comps as a current market indicator. Nikki presents them as historical data and then applies the analytical skills she built over thirty years to project where the market is actually heading based on days on market, inventory levels, pricing trends, and seasonal patterns.
That forward-looking analytical framework is what she brings to pricing conversations that most agents cannot replicate. She has had sellers seek her out specifically for that capability. In a market where pricing mistakes are expensive and sitting time compounds the damage that skill is genuinely valuable.
What the Current Sarasota Market Actually Looks Like
Nikki is honest about what she is seeing. There is significant inventory in many parts of the market right now. She is not seeing the market improve meaningfully and she is hopeful but not certain that fall and winter will bring better conditions. What she is seeing clearly is that pricing is the primary variable separating properties that sell quickly from properties that sit.
Well-priced properties are still generating multiple offers even in a market where plenty of listings are sitting. The good houses are still going quickly. The ones priced based on what sellers want rather than what the market will pay are accumulating days on market and the problems that come with it.
She describes the deterioration cycle clearly. Overprice and the property sits. The longer it sits the more buyers expect a deal when they finally show interest. Price reductions signal distress and attract buyers looking to capitalize on that distress. The seller ends up in a worse negotiating position than if they had priced correctly from the start and the emotional toll of watching a listing stagnate is real.
She is also increasingly selective about which listings she takes. If a seller is not genuinely motivated to sell and will not price the property based on market reality the listing is likely to expire. That outcome is bad for the seller emotionally and financially and it is bad for Nikki's time and marketing investment. She would rather pass on those listings and maintain the relationship than take them and watch them fail.
The Pre-Inspection and Title Search Strategy
One of the most practical pieces of advice Nikki offers sellers is to get a pre-inspection and a title search done before the listing goes active. The goal is to surface anything that could derail a closing during the due diligence period and address it in advance.
The standard sequence is list, go under contract, do the inspection, and then renegotiate based on what the inspection finds. Nikki's approach is to compress that renegotiation opportunity by knowing what is there before the buyer does. Fix the items that make sense to fix. Disclose the ones that cannot be fixed. Remove the ability of the inspection to become a second negotiation.
It may take an extra week to get the house on the market. It can save thousands of dollars and eliminate the stress of a deal that goes sideways at the due diligence stage because something unexpected appeared. Dennis reinforced this as a pattern he sees repeatedly from the lending side. Proactive sellers close more cleanly than reactive ones.
On Online Valuations and What They Cannot Tell You
Nikki addresses the online valuation question with the nuanced perspective of someone who spent thirty years looking at what goes into a real appraisal. The aggregated online estimates have gotten better as more data flows into their systems, including formatted appraisal data that is now uploaded in standardized ways. They are more accurate than they used to be.
But they have never been in your house. They cannot see the kitchen renovation quality. They cannot see the deferred maintenance. They cannot see the view, the floor plan, the traffic noise from the nearby road, or the dozens of other factors that a trained appraiser or experienced agent accounts for when establishing a defensible value. Online estimates create false hopes when they are high and create unnecessary anxiety when they are low. Neither outcome serves the seller or the buyer well.
Fannie Mae and Freddie Mac's collateral underwriting systems are more sophisticated than consumer-facing estimates but they are still proprietary and not accessible to most market participants. Nikki and Dennis both note that those systems provide lenders with a confidence score on appraisals based on comparable data that the system can access. That is meaningfully better than a back-of-the-envelope price-per-square-foot calculation but it is still not a substitute for professional judgment applied to a specific property with specific characteristics.
How She Works With Buyers
Non-negotiable number one is pre-approval. There is no value in falling in love with a house you cannot buy. Nikki will not show properties to buyers who have not established their financing position because doing so creates emotional attachment to outcomes that cannot be achieved.
Her offer construction is situational and strategic rather than formulaic. She finds out what matters to the seller. Do they need a quick close or do they need ninety days? She looks for terms her buyers can offer that align with what the seller actually values, which is not always the highest price. A clean offer with favorable terms can win over a higher offer with complications the seller does not want to manage.
For buyers who are short on cash she structures seller concession requests into the offer. For buyers who need a lower payment she explores rate buydown options that the seller can fund. For cash buyers she focuses the entire analysis on nailing the value to protect them from overpaying in a market where they have the leverage of certainty and simplicity.
When a well-priced property comes available she prepares her buyers to move. The good ones are still going quickly. The buyer who is pre-approved, has reviewed the disclosure documents, understands the value, and has a strategic offer ready is the buyer who wins.
On Pricing to Generate Multiple Offers
One of the counterintuitive insights Nikki shares is the relationship between list price and sale price on properties that generate competition. Pricing at or slightly below market value in a market where demand exists often produces multiple offers. Multiple offers produce a final sale price that can exceed what a higher initial list price would have achieved because competing buyers drive the outcome rather than a single buyer negotiating from a position of sole interest.
She acknowledges this is scary for sellers. It is their money and their biggest asset and the instinct is to hold onto every possible dollar by starting high. But she points out that the seller who overprices their house is the only bidder for their own property. Every dollar of overpricing is money that has to come back out through price reductions and each reduction invites buyers to expect more. The math of selling quickly at fair value is often better than the math of sitting for months and reducing to a similar number while accumulating carrying costs and buyer skepticism along the way.
What She Does When She Is Not Selling Real Estate
Nikki plays guitar, which she freely admits is not her best skill. She does food photography and runs a food blog. She enjoys the beach, which is most of the reason she moved to Florida in the first place. She notes with some humor that she went from having too much time on her hands when she first arrived in Florida to finding real estate far more demanding than she ever anticipated. She is busy and she is enjoying the challenge of building something.
Her advice to anyone considering getting into real estate is simple and honest. It is hard work. It is not a lifestyle of showing houses and going home. The visible part of the job is a small fraction of what the job actually requires. If you are willing to put in the work that is not visible you can build something meaningful. If you are getting in for the wrong reasons it will wear off quickly.
How to Reach Nikki Medlin
Call or text 941-318-7600. Visit nikkimedlin.com. She is direct, data-driven, and particularly skilled at helping sellers and buyers understand where the market actually is rather than where they hope it is.
Dennis Wells works with buyers throughout the Sarasota and Gulf Coast area on mortgage financing. Reach out to Dennis Wells to connect on the lending side of any transaction.
Sources
SarasotaAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|