Your Local Mortgage Lender
Located in Sarasota, Florida
Personalized Mortgage Experience
Dennis Wells offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Sarasota, Florida.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
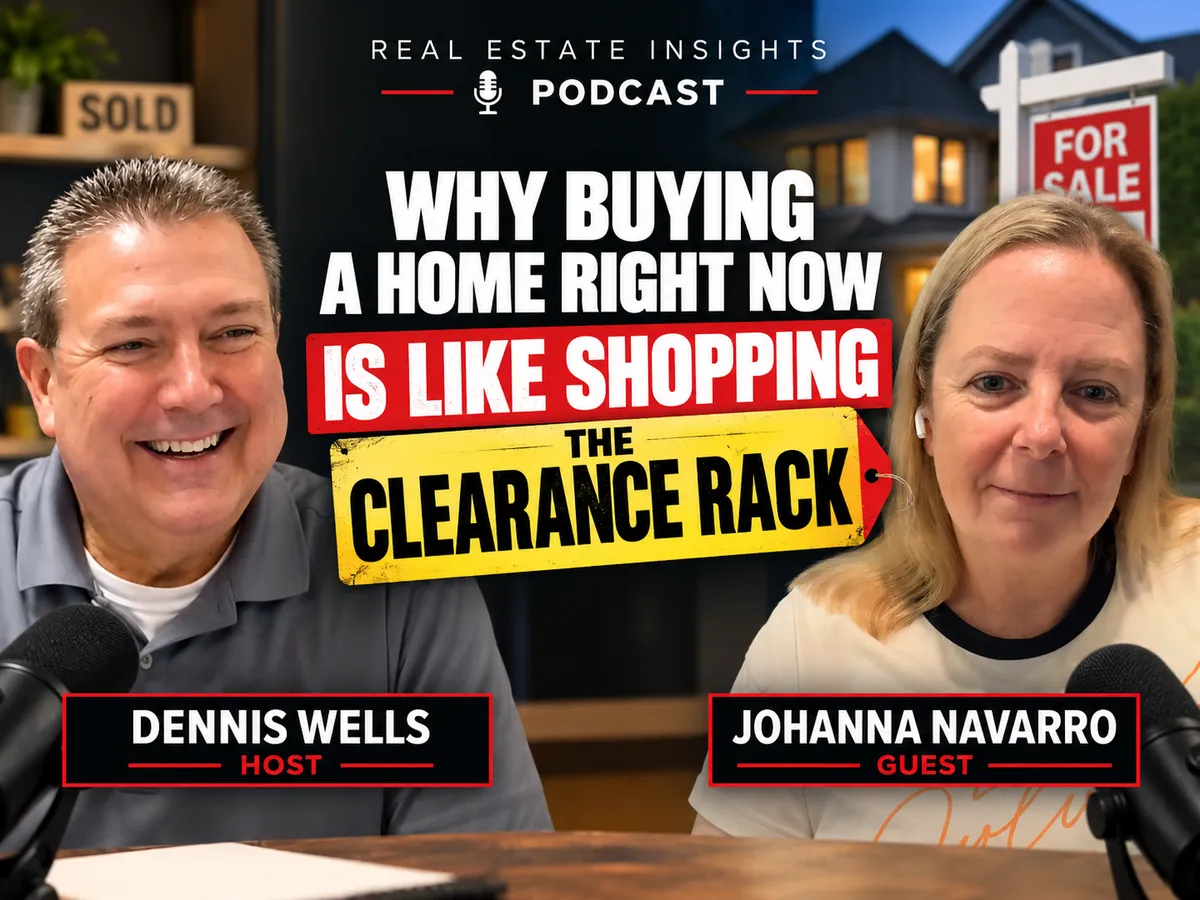
Dennis Wells Talks Wesley Chapel Market, USDA Loans and Rate Buydowns With Johanna Navarro
From the Financial Sector to Florida Real Estate
Dennis Wells welcomed Johanna Navarro of Kings and Associate Realty to the podcast for a conversation about buying strategy in the Wesley Chapel area, why homeownership is a wealth building tool, and how USDA loans and seller-paid rate buydowns are opening doors for buyers right now.
Johanna started in real estate in July of 2017 after seven years working in the financial sector with investments. Her college degrees are in sociology and psychology, and she says the combination of finance, sociology, and psychology has been a major asset. It helps her understand what clients are not saying, how buyers think when she is advising sellers, and what sellers are likely to accept or reject when she is representing buyers.
Listening for What Buyers Do Not Put on the List
Buyers often arrive with a list of bedrooms, bathrooms, square footage, and a fenced yard. Johanna says the real preferences emerge while touring homes. A buyer may mention they dislike brown cabinets or only want carpet in the bedrooms. Picking up on those details, which never made the original list, is part of the job, and it often leads to aha moments for clients along the way.
Why Higher Rates Can Still Be an Opportunity
Johanna sees interest rates as the biggest challenge right now, though she says it is not really a challenge for an educated buyer. Rates are near a six-year high, but she bought her first home at 13%. Her point is that buyers are not married to their rate. They can refinance when rates fall, but they will be locked into the purchase price. When rates come down, prices tend to rise, so buying in a market with less competition and refinancing later can save thousands.
Dennis agrees and notes that a fixed principal and interest payment stays the same for the life of the loan while rent tends to rise every year. Even at the Federal Reserve’s 2% inflation target, the purchasing power of that payment shrinks over time. He adds that getting rates much below the mid 5s generally requires very accommodative Fed policy, which is not what the market has today.
Seller-Paid Buydowns and Cash Back at Closing
Johanna has had a strong year negotiating seller-paid rate buydowns. With market rates right around 7%, she has gotten sellers to pay for buydowns that bring buyers into the 5.25% range. One recent buyer even received a check for $430 at the closing table. With the right agent and a lender who offers different products, she says buyers can purchase with very little or no money down. Dennis points out that sellers can pay closing costs, fund a buydown, or both, which lets buyers tune their cash to close and monthly payment to where they want them.
Homeownership as a Wealth Building Tool
Johanna believes all wealth starts with homeownership. She walks through an example of a first home bought at $300,000 that grows to $450,000 or $500,000 over seven years. The owner uses the equity from paydown and appreciation to put roughly $200,000 down on a $500,000 home, and the cycle repeats. Older sellers do the reverse, selling homes at $750,000 to $950,000, buying a $400,000 home, and keeping the difference for retirement.
Dennis shares that the net worth of homeowners is dramatically higher than that of renters, and that outside the 2008 credit crisis, national home values have fallen in only two years since World War Two, with both declines combined under 1%. Johanna notes that the average time in a home has stretched from about five years to about seven, partly because of owners holding on to very low rates. She also reminds buyers that a first home does not have to be a forever home. Her own daughter looked back years later at townhomes that sold for $75,000 to $80,000 and now sell for $350,000 to $400,000.
USDA Loans Are Not Just for Farms
Johanna loves the USDA loan as a first-time buyer product. It offers no money down, competitive rates, and affordable mortgage insurance, and buyers can often have the seller cover closing costs. A buyer with around $5,000 for inspections and other items can get started. Many areas near her, including Dade City, Plant City, Zephyrhills, and parts of Land O’ Lakes, are USDA eligible. Buyers can check the USDA website map to see eligible areas. Despite the name, you do not have to buy a farm, and a family of two or three can often have a solid income and still qualify.
The Outlook for Wesley Chapel and Florida
Johanna says Wesley Chapel is a micro market with stable prices, while some outlying areas are still climbing. Businesses and people continue moving to Florida, and she has helped more buyers relocating for work this year than ever. Having worked in investments, she views markets as cyclical, roughly on an eight year span, and expects the market to resume rising once higher rates ease. Dennis adds that geopolitical conflict and its effect on oil, diesel, and food costs have added uncertainty, but the Fed’s focus on employment and inflation appears to be moving in the right direction.
She likes to describe today’s market as buying on clearance.
How to Reach Johanna Navarro
Johanna can be found on social media at Johanna Navarro Realtor, or by call or text at 813-299-9870. She is with Kings and Associate Realty and serves buyers and sellers in the Wesley Chapel area.
Dennis Wells works with buyers across Gulf Coast Florida on mortgage financing, including USDA loans and seller-paid buydown strategies. Reach out to Dennis to talk through the payment and cash to close numbers that work for you.
Sources
USDA.gov
Realtor.com
FreddieMac.com
FloridaRealtors.org
ConsumerFinancialProtectionBureau.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

