Your Local Mortgage Lender
Located in Sarasota, Florida
Personalized Mortgage Experience
Dennis Wells offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Sarasota, Florida.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
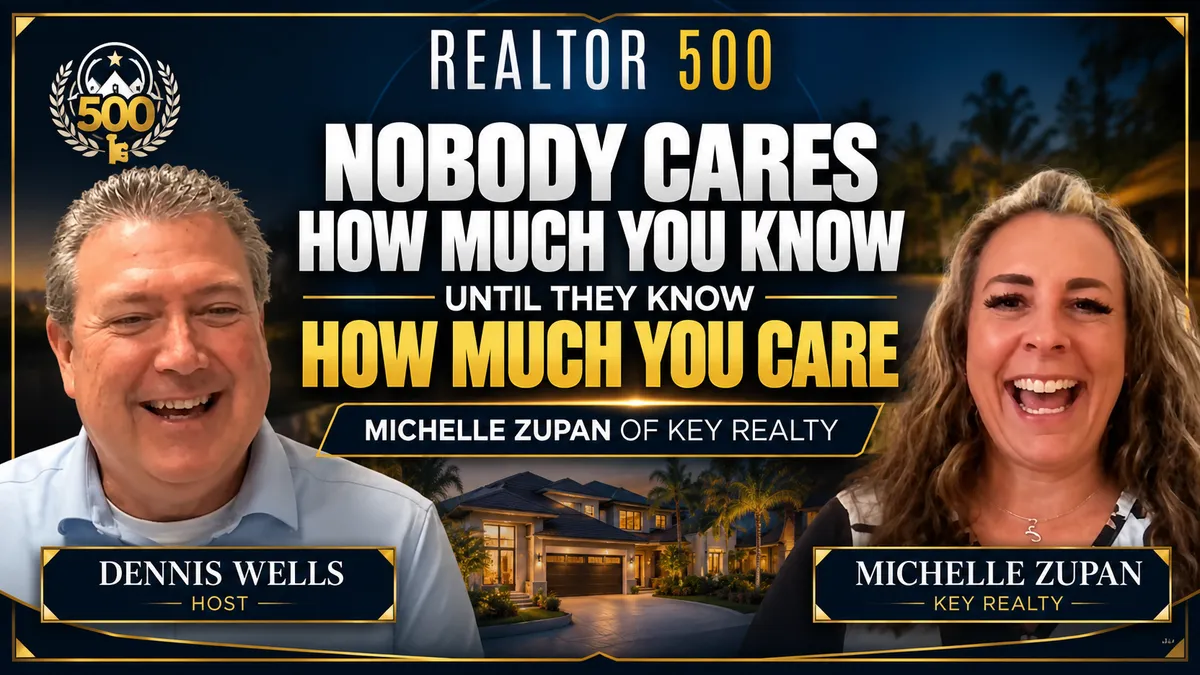
Dennis Wells Talks Northwest Indiana Real Estate and Community-First Business Building With Michelle Zupan of Key Realty
The Agent Who Built a Hundred Percent Referral Business by Showing Up
Dennis Wells welcomed Michelle Zupan of Key Realty to the podcast for a conversation about what eight and a half years in the Northwest Indiana real estate market has taught her, what the market looks like right now for buyers and sellers, and how she built a business that runs entirely on referrals by doing something simpler and harder than most agents attempt. She just shows up.
Michelle came to real estate as a backup plan. She was in a management role at a local company when signals started pointing toward bankruptcy and she and her husband decided to get their licenses together as a contingency. The company did go under. The backup plan became the career. Her husband stayed in his full-time role but the real estate license turned into eight and a half years of building something that now sustains itself entirely through the relationships she has cultivated in her community.
What She Has Watched Change in Northwest Indiana
When Michelle started in real estate a two hundred and twenty-five thousand dollar home was a genuinely good house in a good neighborhood. That same two hundred and twenty-five thousand is now more of an entry level price point and the market has shifted around it in ways that require different conversations with both buyers and sellers than she was having when she started.
The fundamentals that have not changed are the ones she keeps returning to. Preparation. Realistic expectations. Genuine care for the people on both sides of the transaction.
What She Tells Buyers in the Current Market
Michelle’s advice to buyers centers on financial sanity rather than maximum borrowing power. Never get into a situation where you are married to a house. The payment should be comfortable enough that you can still go out to dinner and still take trips. Save enough for the down payment and closing costs so nothing surprises you halfway through. And do not settle for a house you do not love just because you are ready to buy.
That last piece matters to her as much as the financial preparation. The goal is not just qualifying for a mortgage. It is finding something that genuinely fits the life the buyer is trying to live.
What She Tells Sellers About Pricing and Presentation
The first week on the market is everything. If showings are not being scheduled within the first week that is the signal to have a conversation about price because the market is telling you something important and ignoring it costs more than adjusting quickly does.
Michelle’s philosophy on pricing is straightforward. Run the comps, price based on what comparable homes are actually selling for, and do not price yourself out of the market chasing a number that the data does not support. Sellers who price correctly from the start do not have to take significant reductions later. Sellers who price too high often end up netting less than they would have with a correct day-one price because the stigma of sitting on the market works against them.
On the presentation side she is equally direct. The first five seconds of walking into a home determines a significant portion of the buyer’s emotional response to everything that follows. The home should sell itself. If she has to sell a house there is probably something that needs to be addressed. The practical list is not glamorous but it matters. Clean and tidy. Smells good. Dishes out of the sink. Laundry off the floor. Space clear enough that buyers can visualize where their furniture goes and where their Christmas tree is going to stand.
That last detail is the one that signals a buyer is falling in love. Once they start mentally placing their Christmas tree in the living room the emotional work is largely done.
What the Northwest Indiana Market Is Doing Right Now
The market is steady and holding strong. Listings are up slightly year over year and prices are holding. Average days on market for new listings is running around eighteen days though higher price points are seeing longer market times as buyers at that level have more options and take more time. Inventory sits at approximately two months which creates a slight seller advantage without returning to the extreme conditions of a few years ago.
Homes are selling at approximately ninety-six and a half to ninety-seven percent of list price. That is a meaningful and healthy number. It suggests that most sellers are pricing correctly or close enough that only a small adjustment is required to close the gap. Dennis notes that nationally somewhere over thirty percent of listings take a price cut before selling and the Northwest Indiana market appears to be performing in the normal range rather than the excessive price reduction territory some markets are experiencing.
The interest rate environment has stayed consistent with what buyers have been navigating for a while and the market has adjusted to that reality. Buyers are present. Sellers are transacting. The market is moving.
How She Grew a Hundred Percent Referral Business
Michelle does not do paid advertising. She does not buy leads. Her business comes entirely from people she knows and from the people those people send her.
The engine behind that is community presence and the inability to say no to someone who needs help. She supports the Four Seasons Fire Department consistently. When a significant fire breaks out she shows up with water, Gatorade, and food for the department. She sponsors golf outings and breakfasts for the local women’s and men’s golf associations. She coordinates a massive Christmas event in the community every year beginning the Saturday after Thanksgiving that includes a lighted parade, Santa, the Grinch, the Elf on the Shelf, a tree lighting, fireworks, a vendor market, and food trucks.
When the tornado hit Maryville she drove an hour through the debris to spend eight and a half hours clearing trees in her parents’ neighborhood. Not because anyone was watching. Because that is what the community needed and she was available to do it.
The principle she articulates is one Dennis has trained on himself from an earlier career. Nobody cares how much you know until they know how much you care. For Michelle that is not a slogan. It is how she actually lives professionally and personally. Buyers and sellers who can see that she genuinely cares about them and about their community do not have to be convinced to trust her. The trust is already there from years of watching her show up.
The Bougie Bros
Michelle’s dogs Bruce Springsteen and Clarence Clemens deserve their own mention because they reveal something about her personality that the professional summary alone does not capture. Bruce came first twelve years ago when her husband who is not a huge dog person bought him for her. The name Bruce Springsteen was a calculated move to make him fall in love with the dog and it worked. Clarence Clemens joined the household three years ago named after the saxophone player from the E Street Band who was known as the Big Man. Clarence weighed approximately as much as a bottle of Coke when he arrived which made the name even better.
They have their own closet. They wear matching outfits. They are spoiled in the most deliberate and guilt-free way. Michelle works hard partly so she can give them the life they deserve since they did not ask to be in her home. Clarence also has a preference for staying home and watching yacht rock videos which is the most specific and relatable pet personality detail this podcast has produced.
How to Reach Michelle Zupan
Michelle is available by text, cell phone, and email at all times except when she is with a client in which case she will get back to you immediately after. She gives every client her complete attention during their time together and she offers the same courtesy to everyone reaching out. Contact Key Realty to connect with Michelle Zupan in Northwest Indiana.
Dennis Wells works with buyers throughout the Gulf Coast Florida area on mortgage financing and welcomes connections with buyers and sellers anywhere he can be a resource. Reach out to Dennis Wells to connect on the lending side of any transaction.
Sources
IndianaAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

