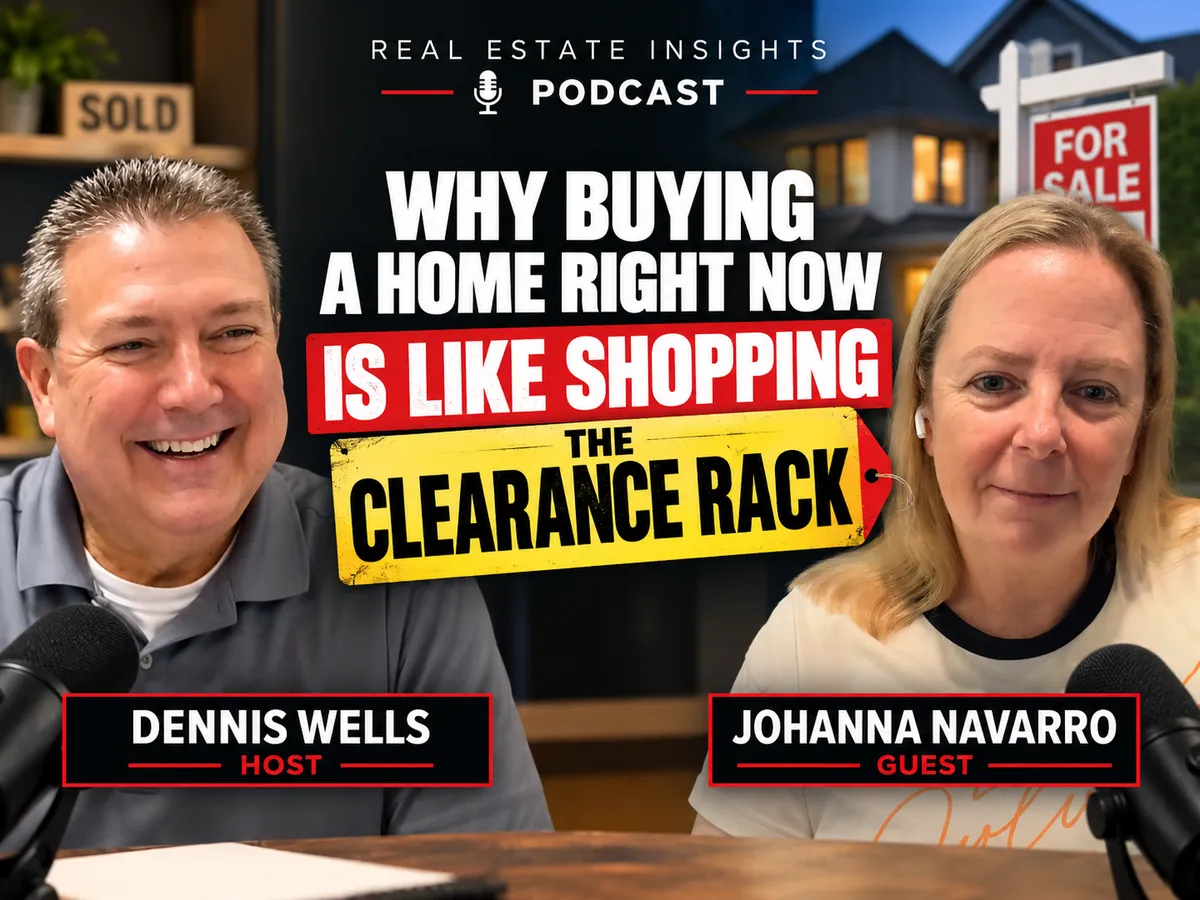
Dennis Wells Talks Wesley Chapel Market, USDA Loans and Rate Buydowns With Johanna Navarro
From the Financial Sector to Florida Real Estate
Dennis Wells welcomed Johanna Navarro of Kings and Associate Realty to the podcast for a conversation about buying strategy in the Wesley Chapel area, why homeownership is a wealth building tool, and how USDA loans and seller-paid rate buydowns are opening doors for buyers right now.
Johanna started in real estate in July of 2017 after seven years working in the financial sector with investments. Her college degrees are in sociology and psychology, and she says the combination of finance, sociology, and psychology has been a major asset. It helps her understand what clients are not saying, how buyers think when she is advising sellers, and what sellers are likely to accept or reject when she is representing buyers.
Listening for What Buyers Do Not Put on the List
Buyers often arrive with a list of bedrooms, bathrooms, square footage, and a fenced yard. Johanna says the real preferences emerge while touring homes. A buyer may mention they dislike brown cabinets or only want carpet in the bedrooms. Picking up on those details, which never made the original list, is part of the job, and it often leads to aha moments for clients along the way.
Why Higher Rates Can Still Be an Opportunity
Johanna sees interest rates as the biggest challenge right now, though she says it is not really a challenge for an educated buyer. Rates are near a six-year high, but she bought her first home at 13%. Her point is that buyers are not married to their rate. They can refinance when rates fall, but they will be locked into the purchase price. When rates come down, prices tend to rise, so buying in a market with less competition and refinancing later can save thousands.
Dennis agrees and notes that a fixed principal and interest payment stays the same for the life of the loan while rent tends to rise every year. Even at the Federal Reserve’s 2% inflation target, the purchasing power of that payment shrinks over time. He adds that getting rates much below the mid 5s generally requires very accommodative Fed policy, which is not what the market has today.
Seller-Paid Buydowns and Cash Back at Closing
Johanna has had a strong year negotiating seller-paid rate buydowns. With market rates right around 7%, she has gotten sellers to pay for buydowns that bring buyers into the 5.25% range. One recent buyer even received a check for $430 at the closing table. With the right agent and a lender who offers different products, she says buyers can purchase with very little or no money down. Dennis points out that sellers can pay closing costs, fund a buydown, or both, which lets buyers tune their cash to close and monthly payment to where they want them.
Homeownership as a Wealth Building Tool
Johanna believes all wealth starts with homeownership. She walks through an example of a first home bought at $300,000 that grows to $450,000 or $500,000 over seven years. The owner uses the equity from paydown and appreciation to put roughly $200,000 down on a $500,000 home, and the cycle repeats. Older sellers do the reverse, selling homes at $750,000 to $950,000, buying a $400,000 home, and keeping the difference for retirement.
Dennis shares that the net worth of homeowners is dramatically higher than that of renters, and that outside the 2008 credit crisis, national home values have fallen in only two years since World War Two, with both declines combined under 1%. Johanna notes that the average time in a home has stretched from about five years to about seven, partly because of owners holding on to very low rates. She also reminds buyers that a first home does not have to be a forever home. Her own daughter looked back years later at townhomes that sold for $75,000 to $80,000 and now sell for $350,000 to $400,000.
USDA Loans Are Not Just for Farms
Johanna loves the USDA loan as a first-time buyer product. It offers no money down, competitive rates, and affordable mortgage insurance, and buyers can often have the seller cover closing costs. A buyer with around $5,000 for inspections and other items can get started. Many areas near her, including Dade City, Plant City, Zephyrhills, and parts of Land O’ Lakes, are USDA eligible. Buyers can check the USDA website map to see eligible areas. Despite the name, you do not have to buy a farm, and a family of two or three can often have a solid income and still qualify.
The Outlook for Wesley Chapel and Florida
Johanna says Wesley Chapel is a micro market with stable prices, while some outlying areas are still climbing. Businesses and people continue moving to Florida, and she has helped more buyers relocating for work this year than ever. Having worked in investments, she views markets as cyclical, roughly on an eight year span, and expects the market to resume rising once higher rates ease. Dennis adds that geopolitical conflict and its effect on oil, diesel, and food costs have added uncertainty, but the Fed’s focus on employment and inflation appears to be moving in the right direction.
She likes to describe today’s market as buying on clearance.
How to Reach Johanna Navarro
Johanna can be found on social media at Johanna Navarro Realtor, or by call or text at 813-299-9870. She is with Kings and Associate Realty and serves buyers and sellers in the Wesley Chapel area.
Dennis Wells works with buyers across Gulf Coast Florida on mortgage financing, including USDA loans and seller-paid buydown strategies. Reach out to Dennis to talk through the payment and cash to close numbers that work for you.
Sources
USDA.gov
Realtor.com
FreddieMac.com
FloridaRealtors.org
ConsumerFinancialProtectionBureau.gov
